Free 108-page deep dive · October 2026
Oriana Power, explained from zero.
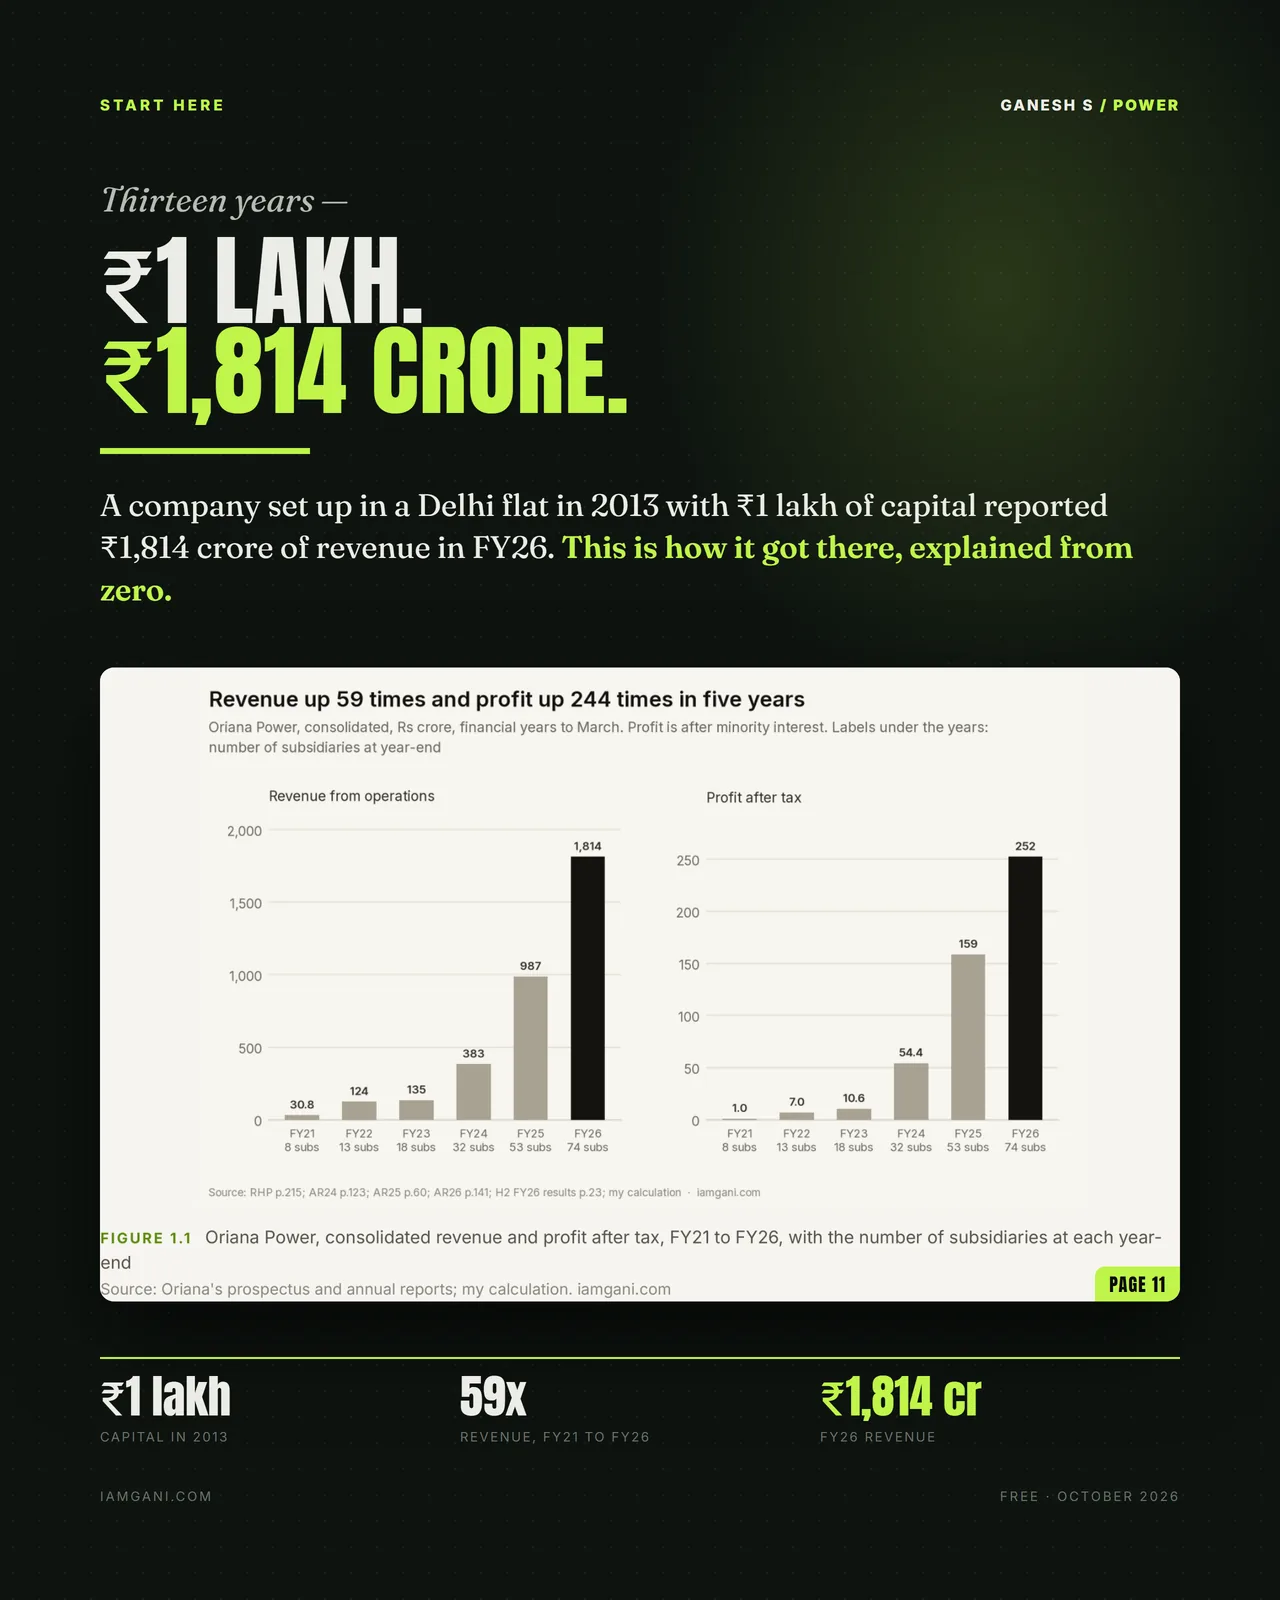
A ₹1 lakh company from a West Delhi flat became a ₹1,814 crore solar group in thirteen years. How it works, where its profit really comes from, and what it could be worth — written for someone who has never read a power-sector filing. Free.
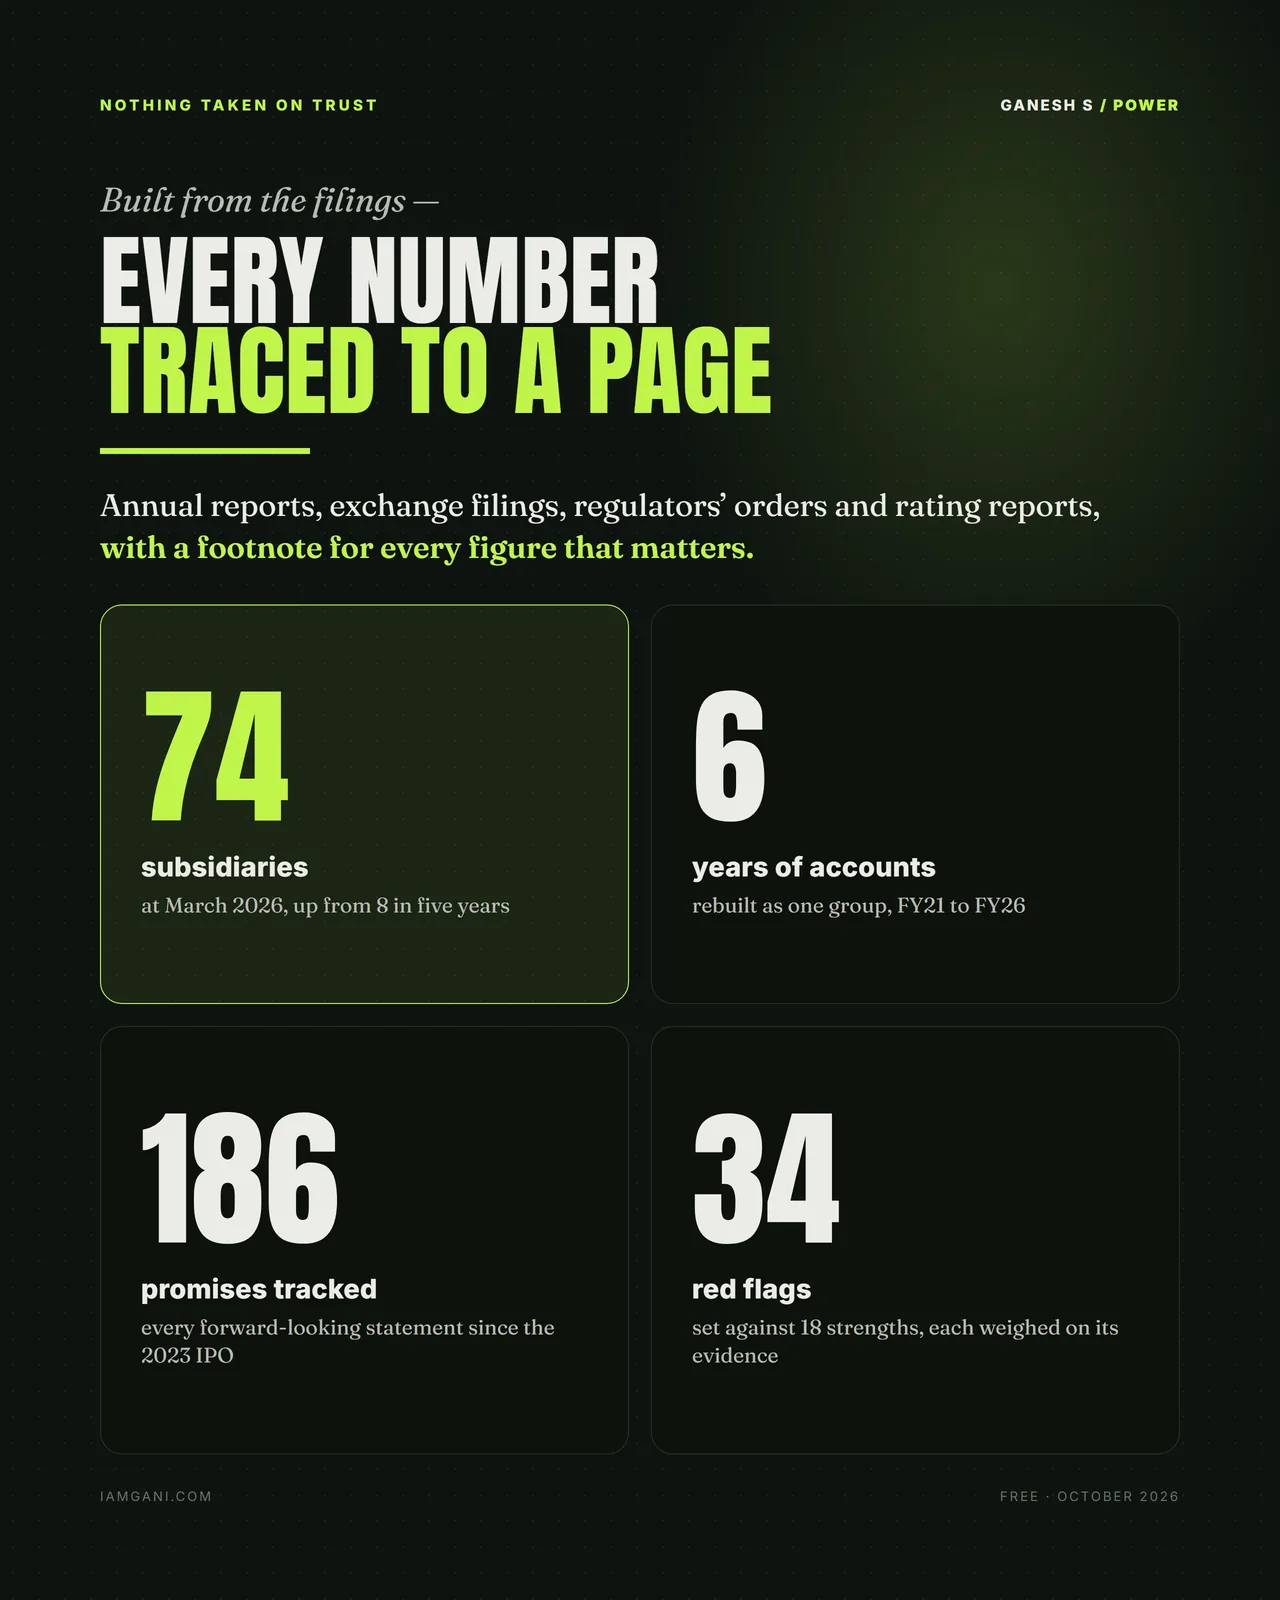
- 74 subsidiaries
- At March 2026, up from 8 five years earlier
- 6 years
- Of accounts, FY21 to FY26, rebuilt as one group
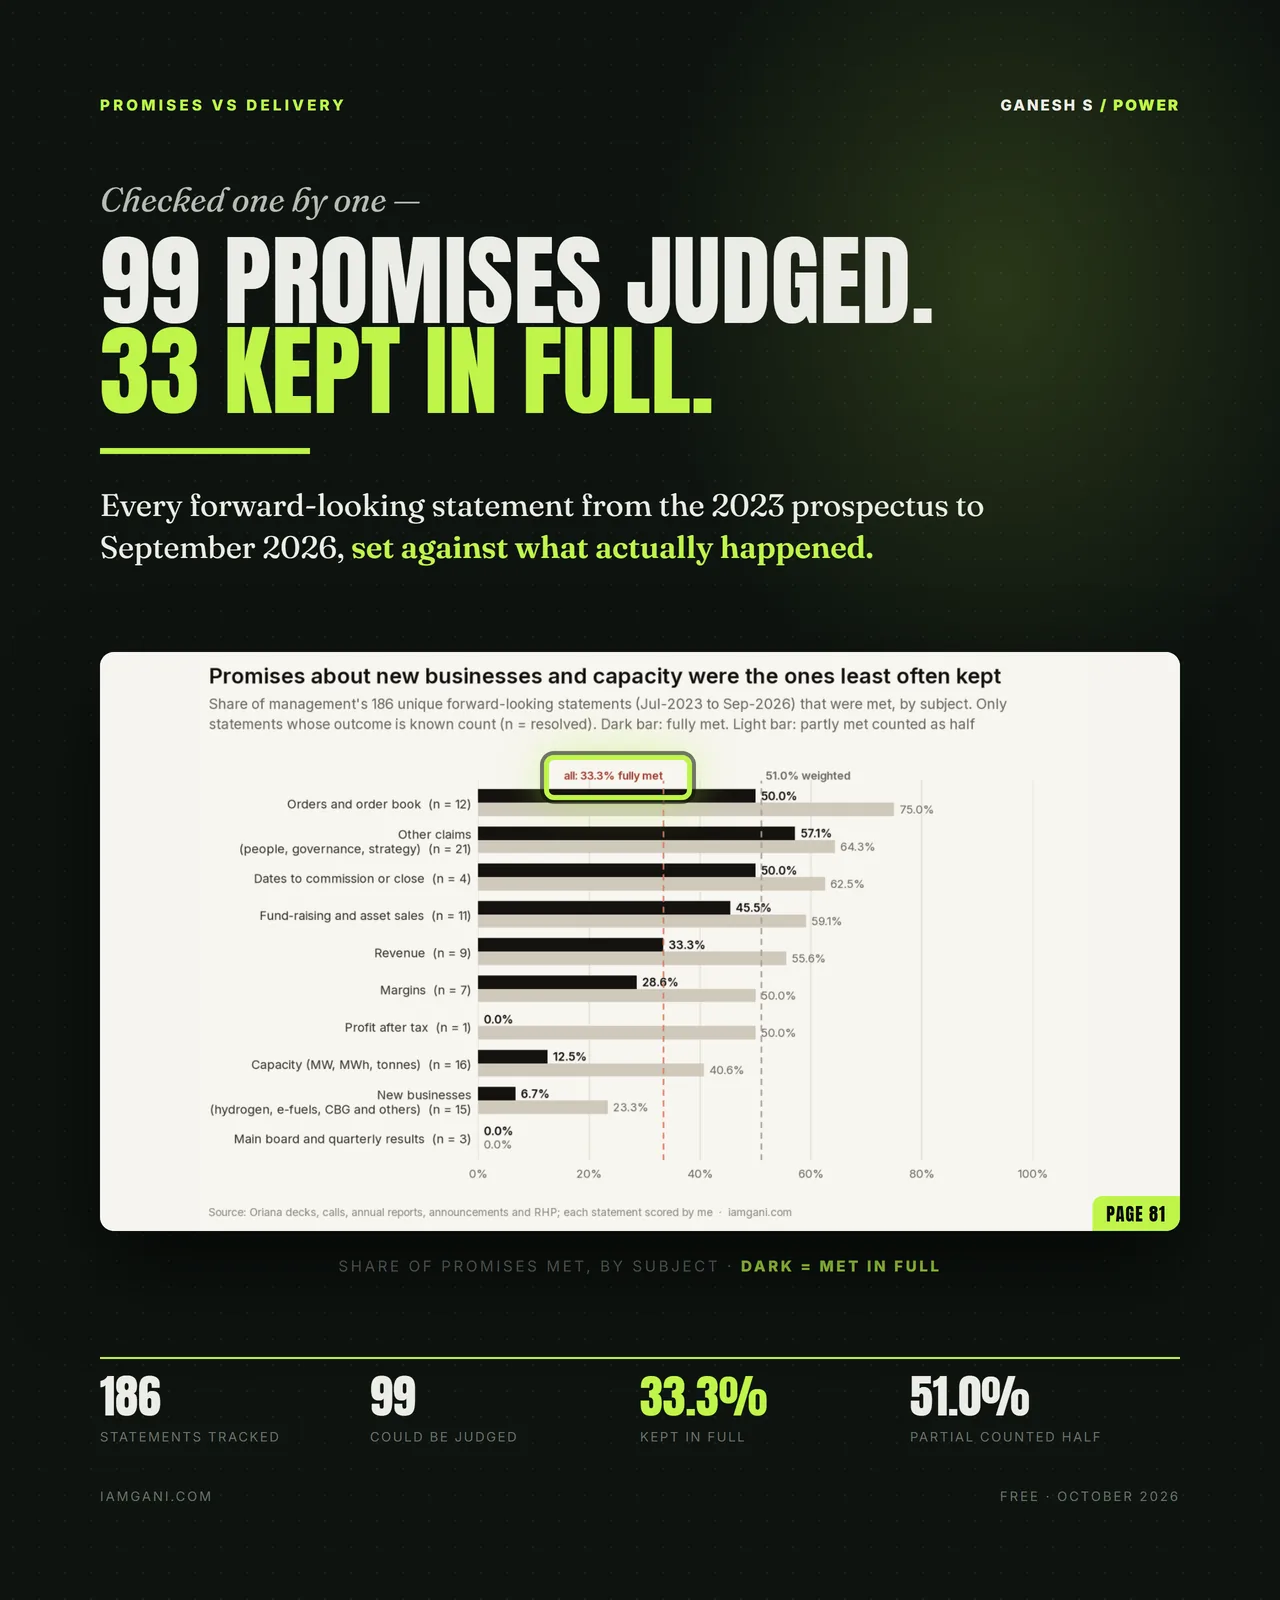
- 186 promises
- Every forward-looking statement since the 2023 IPO, tracked
- 34 vs 18
- Red flags set against strengths, each weighed on its evidence
The customer is often itself —
a solar builder that builds for its own companies.
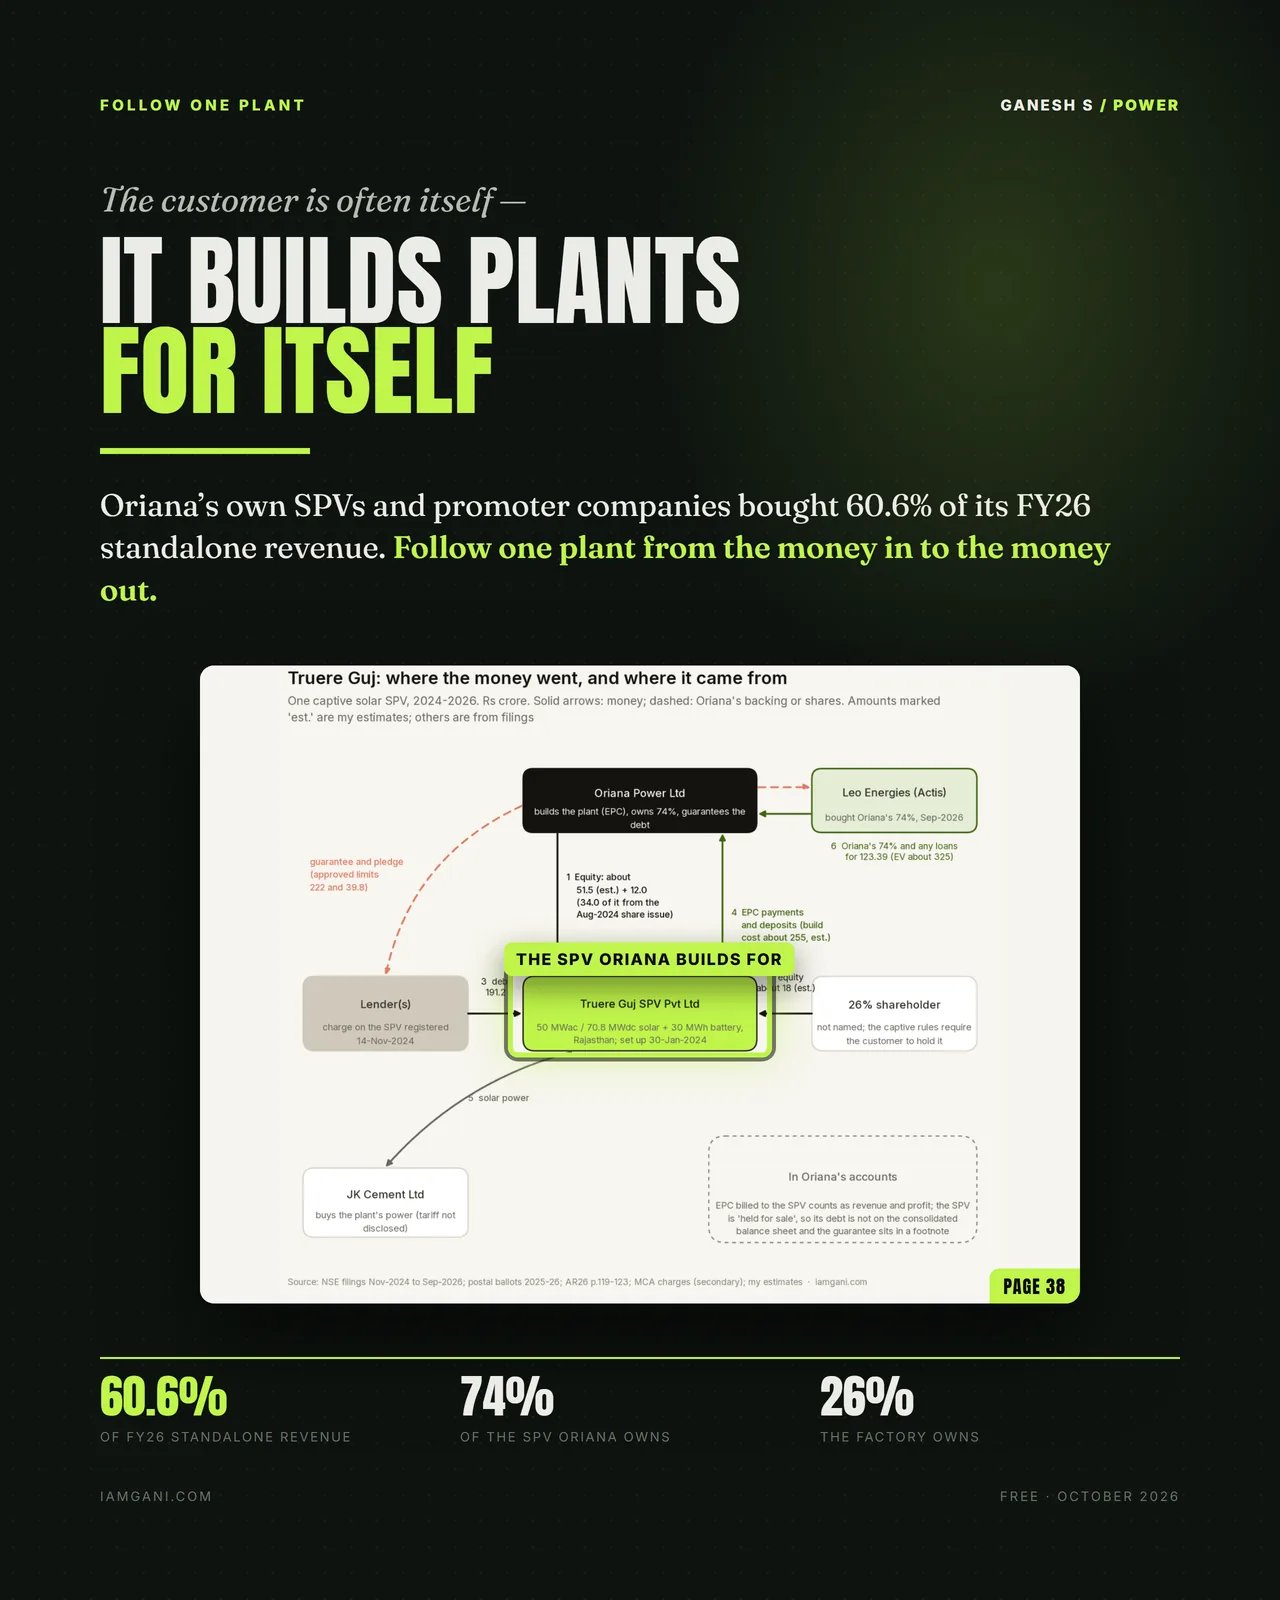
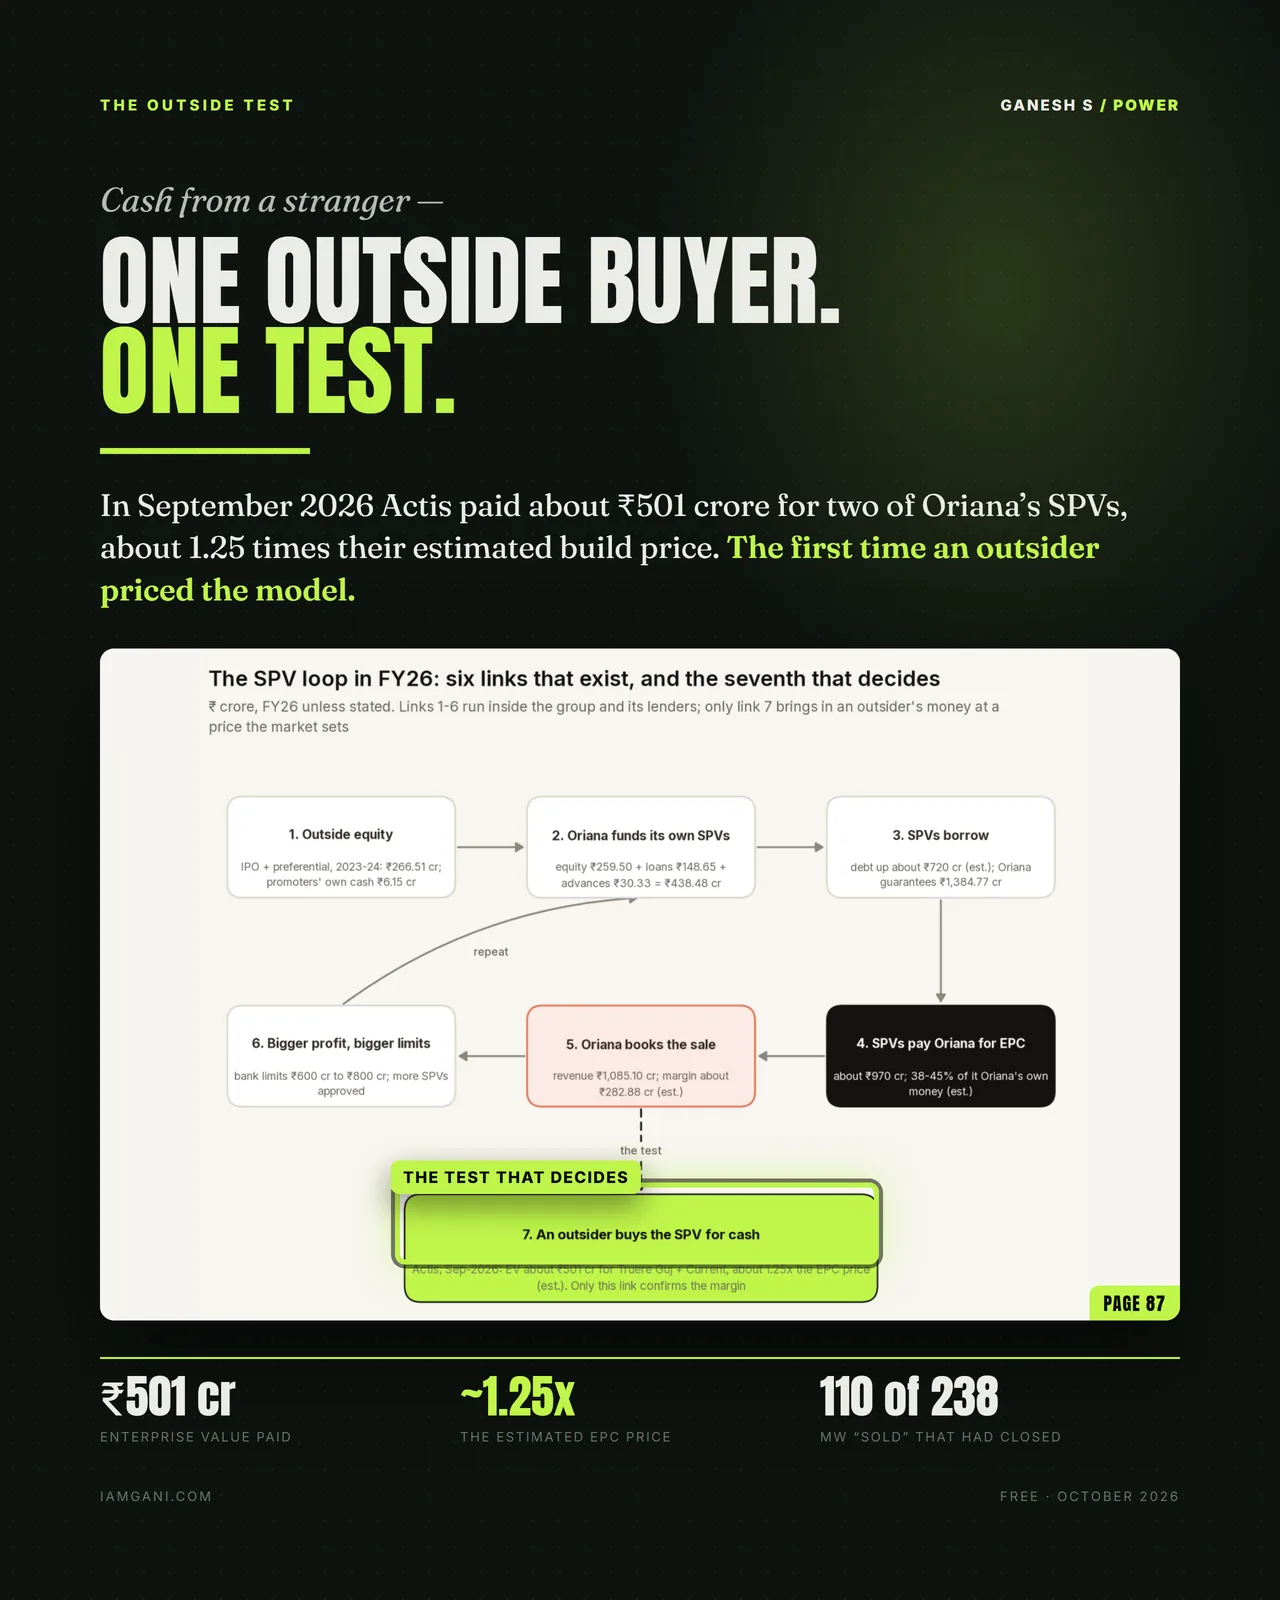
A factory saves on power from a solar plant it partly owns — but only if it holds at least 26% of the plant's company and uses most of its output. So each plant gets a company of its own. Oriana holds the other 74%, builds the plant, and books the bill as its own revenue and profit, planning to sell its stake later.
In FY26 those plant companies and the promoters' own firms bought 60.6% of Oriana's standalone revenue. This study follows one plant from the money in to the money out, rebuilds six years of accounts with those companies counted inside the group, and ends on the one question almost everything turns on: will outsiders keep paying, in cash, for the plants Oriana builds for itself?
What's inside
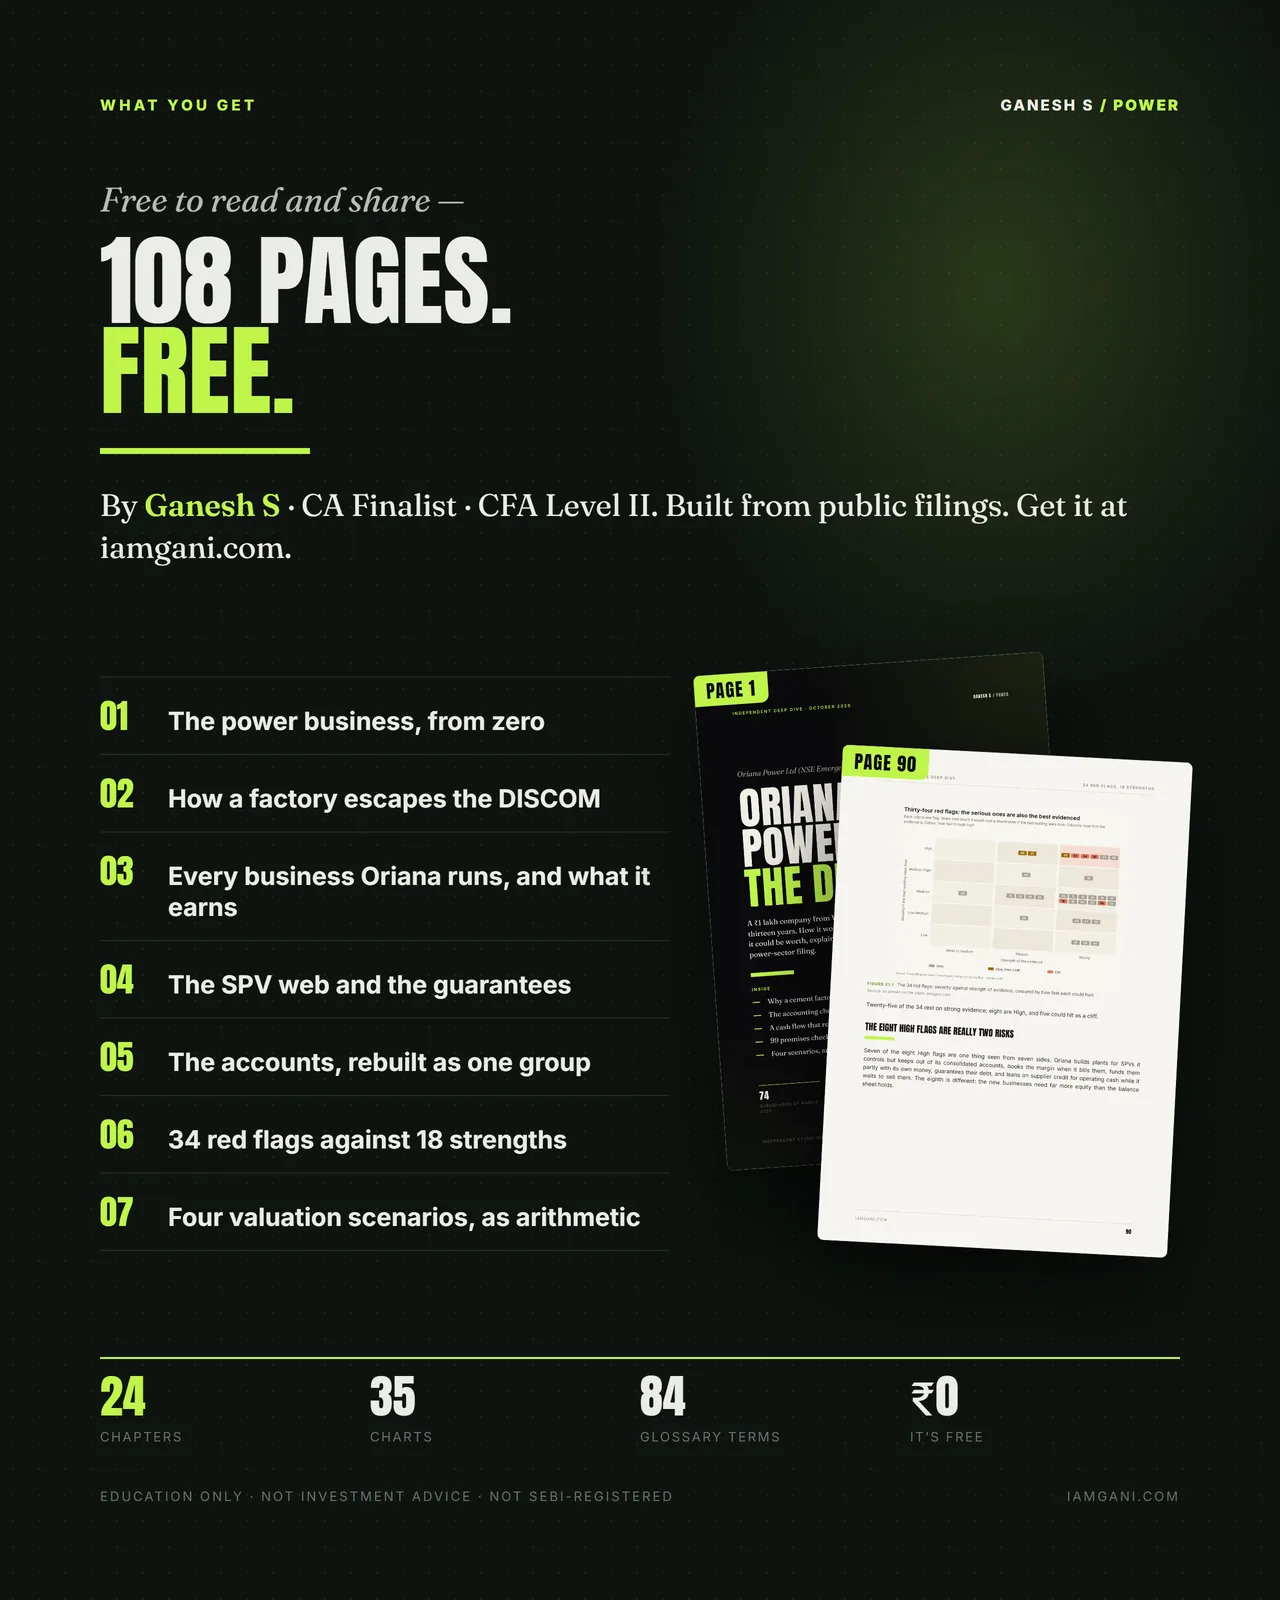
108 pages · 24 chapters · 35 charts
Part I · Meet Oriana
A company that started with ₹1 lakh of capital and a flat in West Delhi. Who it is, what it sells, and the question that runs through the rest of the report.
Part II · The power business, from zero
How electricity is made, priced and sold in India, why factories overpay for it, how one escapes its DISCOM, and four ways to make money from one solar plant.
Part III · Inside Oriana
The people and the shareholders, one plant followed end to end, then each business in turn: solar construction, owned plants, batteries, ammonia, biogas and the overseas plans.
Part IV · Follow the money
Where it turns investigative: the cash-flow puzzle, the SPV web, the family supplier and the guarantees, the accounts rebuilt as one group, promises against delivery, and a forensic read.
Part V · What it might be worth
Where each business could go, my own arithmetic under four sets of assumptions, and what to watch next. Not a forecast and not a price target — it shows which assumptions the value turns on.
Plus · nothing taken on trust
An 84-term glossary, a "before you start" page for readers new to filings, and a source note on every figure that matters, naming the document and the page.
Among other things, you'll find
- Why a cement factory owns 26% of the plant that powers it.
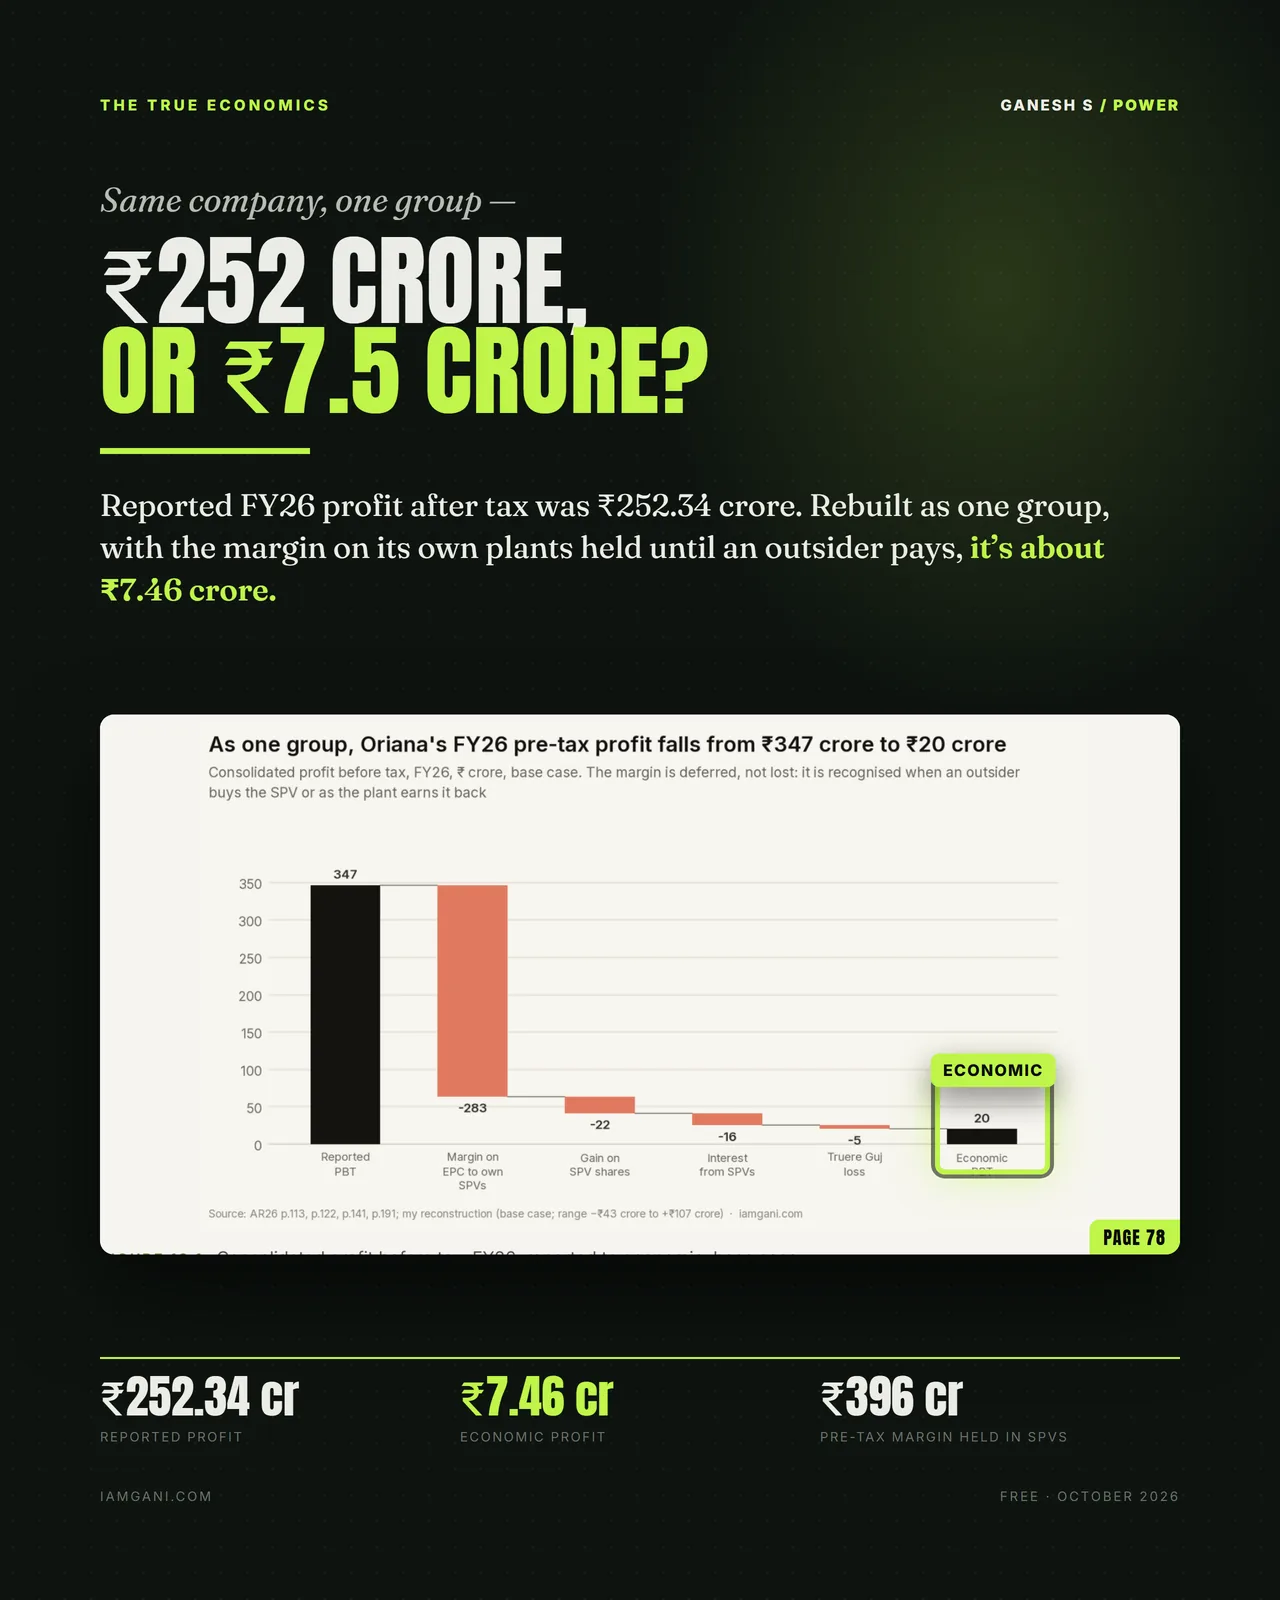
- The accounting choice that turns ₹252 crore of profit into about ₹7.5 crore.
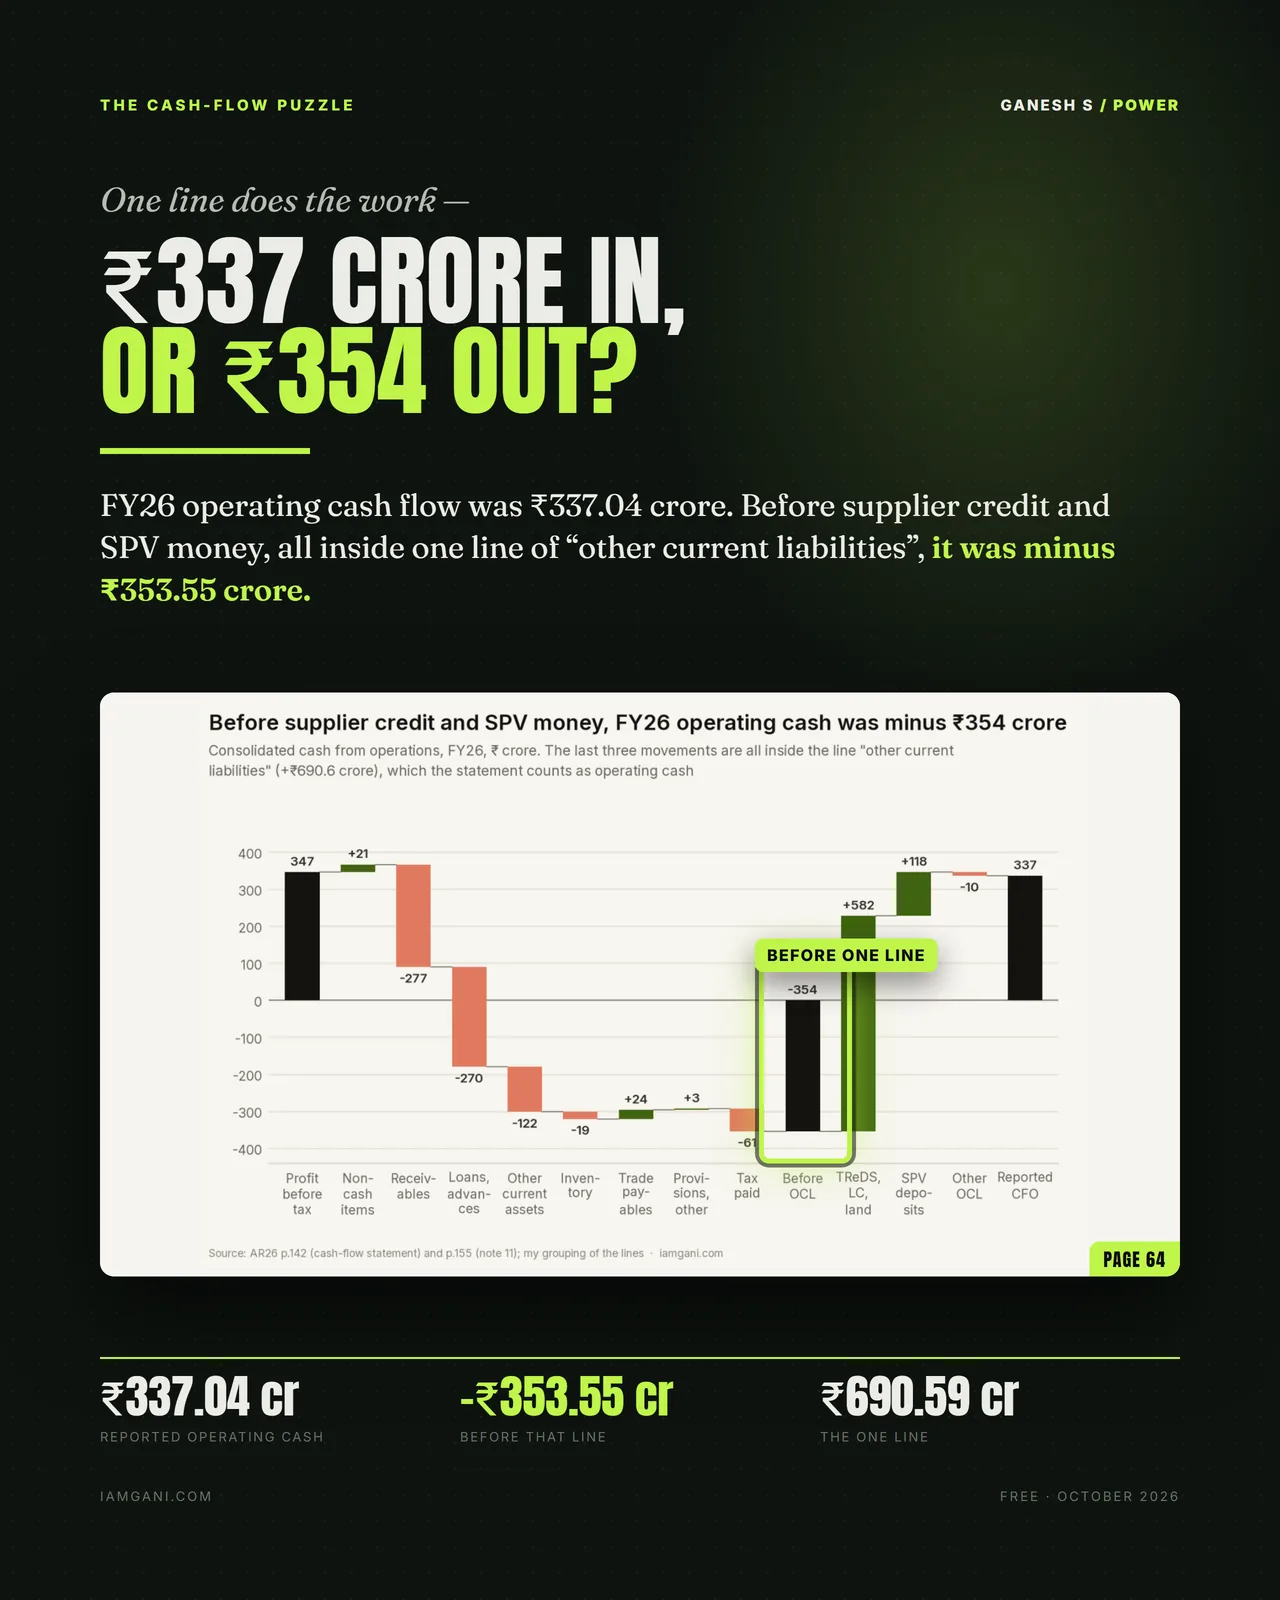
- A cash flow that rests on one line of supplier credit.
- 99 promises checked against what happened. 33 were kept in full.
- Four scenarios, and the one number that decides them all.
Get the deep dive
Enter your email, get the PDF.
108 pages · free · yours to share in full. Not advice — a map of where to dig.
By Ganesh S · Passed CFA Level II · CA Final (May 2027). Built from published filings only. Education only, not investment advice; I am not SEBI-registered. No rating, no price target, no call on the shares — read the disclaimer at the front of the report first.